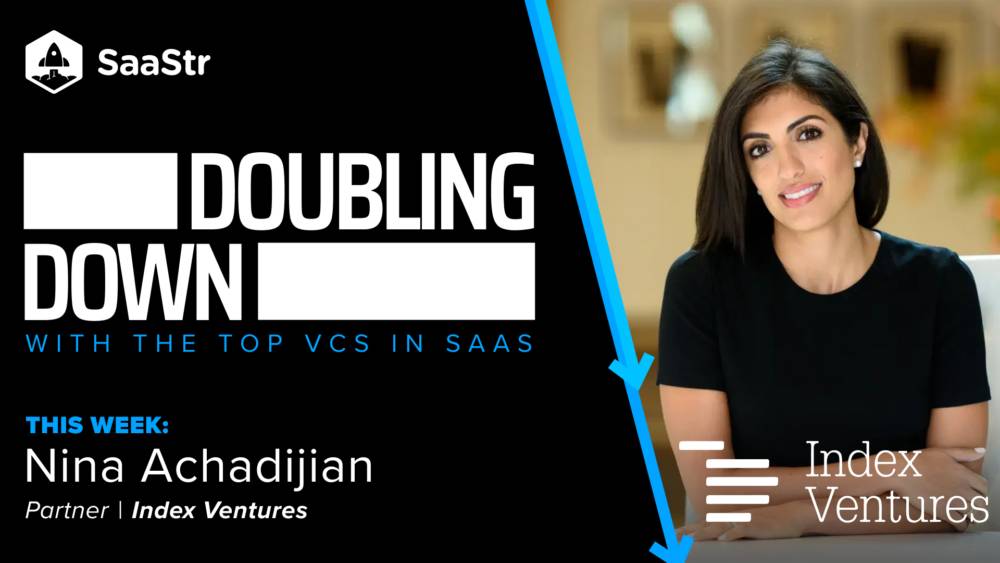
Note on spelling: The investor is most commonly listed in public records as Nina Achadjian. This article keeps the requested headline spelling while using the verified spelling throughout the story.
In venture capital, “doubling down” is not just a poker-flavored phrase that makes investors sound cooler at conferences. It is a philosophy. It means spotting a market before the crowd arrives, backing a founder before the spreadsheet looks obvious, and staying close when the company hits the messy middle. Nina Achadjian, Partner at Index Ventures, has built her career around that kind of conviction.
Achadjian is known for investing across seed, venture, and growth stages, with a focus on AI, robotics, software for hardware, enterprise software, and vertical SaaS. Her sweet spot is wonderfully unglamorous in the best possible way: industries still running on pen, paper, phone calls, spreadsheets, and software that looks like it was designed during a lunch break in 1998. In other words, huge markets hiding in plain sight.
That makes her story especially relevant now. The startup world has shifted from “growth at all costs” to “show me the durability.” Founders are being asked to build real products, serve real customers, and prove real economics. Achadjian’s investment style fits this era because it is rooted in empathy, operational understanding, and a deep interest in overlooked workflows. She is not chasing buzzwords for sport. She is looking for the quiet pain points that become giant businesses once someone finally solves them.
Who Is Nina Achadjian?
Nina Achadjian is a partner at Index Ventures, one of the world’s best-known venture capital firms, with a portfolio that includes companies such as Figma, Revolut, Wiz, Anthropic, Discord, Adyen, Datadog, and Roblox. At Index, she works with companies including ServiceTitan, Physical Intelligence, Anthropic, Quilter, Gong, Vizcom, Transcend, and others.
Her path into venture was not a straight “Stanford hoodie to Sand Hill Road” story. She graduated from Harvard University with a degree in government, began her career as a bond trader in New York and London, worked at Google as an FP&A lead for the AdSense sales organization, and later founded HIVE Ventures, an early-stage fund focused on Armenian entrepreneurs. That combination matters. Finance taught her discipline. Google exposed her to scale. HIVE gave her founder empathy before she became a full-time institutional investor.
Before joining Index, Achadjian saw firsthand how difficult it could be for talented founders outside the usual Silicon Valley circles to access capital, mentorship, and networks. HIVE Ventures became a bridge for Armenian entrepreneurs in Armenia and the United States, investing in dozens of companies and helping connect founders with experienced technology leaders. That experience seems to show up again and again in her current work: she looks for ambition in places where others may not be looking closely enough.
The Index Ventures Context
Index Ventures has long positioned itself as a firm that invests in people, not just categories. Its public philosophy emphasizes founders as the real engines behind enduring companies. That is not just branding fluff, although venture firms do love a good sentence with the word “visionary” in it. In Achadjian’s case, the idea is visible in the way she discusses founders: curiosity, customer empathy, and a growth mindset are not decorative traits. They are underwriting criteria.
When Index announced Achadjian’s promotion to partner in 2020, the firm highlighted her role in developing its vertical SaaS thesis and her investments in companies such as ServiceTitan, Shopmonkey, and Double. The announcement also credited her with building programs inside the firm, including angel-investment initiatives and founder-focused events. That is an important clue: Achadjian is not only picking companies; she is shaping the machinery around how companies get discovered, supported, and scaled.
Why Vertical SaaS Became Her Signature Theme
Vertical SaaS is software built for a specific industry rather than a broad function. Think software for home services, auto repair shops, agriculture, architecture, medical documentation, construction, logistics, or other specialized markets. Horizontal software says, “Here is a tool for everyone.” Vertical software says, “Here is a tool for your exact job, your exact customer, and the weird form you have to fill out every Thursday.”
Achadjian’s interest in vertical SaaS is practical. Many large sectors still depend on outdated workflows, fragmented tools, and manual processes. A founder who understands those pain points can build software that becomes the operating system for an entire industry. If that platform also embeds payments, financing, compliance, customer communications, or data intelligence, the company can become far more than a simple app. It can become infrastructure.
ServiceTitan is the clearest example. Built for trades businesses such as HVAC, plumbing, and electrical services, ServiceTitan helped modernize a sector that is enormous but historically underserved by software. The company went public in December 2024, and its shares jumped sharply in their Nasdaq debut. For Achadjian, who had served on ServiceTitan’s board since 2018, the IPO became more than a liquidity event. It was a public-market validation of the vertical SaaS thesis: boring workflows can become beautiful businesses. Boring, in this case, is a compliment. Boring pays invoices.
ServiceTitan: The Case Study That Explains the Thesis
ServiceTitan’s story has a useful founder-market-fit lesson. Its co-founders, Ara Mahdessian and Vahe Kuzoyan, built the company to help trades businesses like the ones their families knew well. That insider understanding gave them a sharper view of the customer than a generic software team might have had. The software addressed scheduling, dispatching, billing, analytics, customer communications, and other daily operations that keep service businesses alive.
From an investor’s perspective, ServiceTitan showed several traits that match Achadjian’s interests: a massive market, a customer base with urgent operational pain, a product that could expand over time, and founders with deep empathy for the people they served. The company’s IPO also arrived during a difficult period for venture-backed technology listings, making its debut especially significant. In a market hungry for proof that software companies could still earn public investor confidence, ServiceTitan brought a very large receipt.
That is the heart of “doubling down.” It is easy to celebrate vertical SaaS after the bell rings on IPO day. The harder move is building conviction years earlier, when the market seems niche, the customer looks unfashionable, and the product category does not yet have a glossy name. Achadjian’s role in ServiceTitan reflects the investor’s version of patience: keep showing up, keep learning the customer, and keep compounding.
From SaaS to AI, Robotics, and Software for Hardware
Achadjian’s current focus has expanded into AI, robotics, and software for hardware, but the pattern remains surprisingly consistent. Whether the market is home services, printed circuit boards, enterprise workflows, or physical AI, the question is similar: where is human effort trapped in repetitive, complex, or underserved work?
Physical Intelligence, one of the companies listed among those she works with, is building general-purpose AI for the physical world. That aligns with a broader shift in venture capital: AI is moving beyond chat interfaces and into robotics, manufacturing, design, logistics, and physical operations. The next big software wave may not live only in a browser tab. It may fold laundry, inspect infrastructure, assist engineers, or help machines understand the real world without needing a custom script for every task.
Quilter is another useful example. The company applies physics-driven AI to printed circuit board design, a bottleneck in electronics development. In 2025, Quilter announced a Series B led by Index Ventures, with Achadjian joining the board. That fits neatly into her larger pattern: find a high-friction technical workflow, back a team with domain expertise, and use software to unlock speed in an industry where speed matters.
What Founders Can Learn From Her Investment Style
For founders, Achadjian’s career offers a few practical lessons. First, customer empathy is not a soft skill; it is a competitive advantage. The best vertical software companies do not simply digitize a form. They understand the emotional rhythm of the work: the missed calls, the messy handoffs, the cash-flow anxiety, the compliance headache, the customer who needs an answer right now.
Second, “unsexy” markets are often only unsexy to outsiders. To the people inside them, they are mission-critical. A plumbing company does not need a poetic brand manifesto. It needs jobs scheduled, technicians routed, invoices paid, customers updated, and margins protected. If software can make that happen, adoption can be powerful.
Third, timing matters, but obsession matters more. Many investors talk about market timing as if they are weather forecasters with better shoes. Achadjian’s portfolio suggests a different lens: find founders who are obsessed enough to survive the early skepticism. If the customer pain is real and the product becomes essential, the market can look much larger later than it did at the first pitch meeting.
The Human Side: Empathy With a Spine
One phrase often associated with Achadjian is the balance of determination and empathy. That balance is rare because venture capital can reward extremes. Some investors are all warmth and no urgency. Others are all pressure and no listening skills. Founders usually need both: someone who understands the emotional toll of company-building and still pushes for sharper strategy, better hiring, clearer positioning, and faster learning.
Achadjian’s background helps explain that mix. Bond trading is not exactly a spa retreat for sensitive souls. Google FP&A requires numerical discipline and operational clarity. Founding HIVE Ventures required community-building, patience, and a willingness to create access where it did not already exist. Put those together, and you get an investor who can talk metrics without forgetting the humans behind them.
Why Her Story Matters in 2026
In 2026, venture capital is being reshaped by several forces at once: AI platform shifts, tighter exit markets, a renewed focus on profitability, global founder ecosystems, and the return of deep technical infrastructure. Achadjian sits at the intersection of these themes. Her work in vertical SaaS connects to durable software economics. Her work in AI and robotics connects to the next computing platform. Her experience with HIVE connects to the globalization of entrepreneurship.
That makes her a useful lens for understanding where venture is going. The next decade may not belong only to consumer apps or broad productivity tools. It may belong to founders rebuilding the operating systems of real-world industries: home services, logistics, agriculture, manufacturing, healthcare operations, electronics design, and physical automation. These are not small markets. They are the plumbing of the economy, sometimes literally.
Experiences and Reflections Related to “Doubling Down”
The phrase “doubling down” sounds bold, but in practice it is often quiet. It looks like taking one more customer call after a long day. It looks like visiting a job site instead of relying on a market map. It looks like asking why an industry still uses paper forms, then discovering that the paper form is not the problem; the real problem is trust, workflow timing, regulation, or payments. The best investors and founders learn to respect that complexity instead of bulldozing through it with a shiny dashboard.
Achadjian’s work suggests that great venture investing is less about predicting the future from a glass tower and more about getting close enough to customers to hear the future before it becomes obvious. For example, the trades market did not suddenly become important when ServiceTitan went public. It had always been important. Homes have always needed heat, air conditioning, plumbing, electrical work, and repairs. What changed was the ability of software to make those businesses more efficient, measurable, and scalable.
That experience applies far beyond venture capital. Anyone building a company can borrow the same mindset. Start with a neglected workflow. Study it until the details become familiar. Talk to people who do the work every day. Notice what they complain about, what they tolerate, what they have stopped imagining could improve. Then build something so useful that it becomes part of their daily rhythm. That is how a narrow product becomes a platform.
There is also a personal lesson in Achadjian’s path. She did not begin as a venture capitalist with a perfect script. She moved from trading to Google to founding a venture fund to joining Index. Each step added a different kind of pattern recognition. In a startup world that sometimes worships linear biographies, her career is a reminder that range can become an edge. Finance, operations, community-building, and investing are not separate chapters; they can become one integrated skill set.
For founders, the “doubling down” experience often comes during the most uncomfortable stage: after the initial excitement but before the market fully believes. This is when customer feedback is contradictory, competitors appear, hiring gets harder, and the product still has gaps large enough to drive a service truck through. The right investor does not simply cheer from the sidelines. The right investor helps the founder decide where to focus, which customers matter most, when to expand the product, and when to say no.
That is why Achadjian’s emphasis on empathy matters. Empathy is not merely being nice. It is the ability to understand the customer, the founder, the market, and the moment with enough clarity to make better decisions. In vertical SaaS, empathy might mean understanding why a small business owner fears switching systems. In AI hardware design, it might mean understanding why engineers distrust automation until it proves itself. In robotics, it might mean respecting the difference between a demo that works once and a system that performs reliably in messy reality.
The broader experience is this: the best opportunities often look inconvenient at first. They require learning unfamiliar industries, translating between technical teams and nontechnical customers, and sticking with markets that do not always produce instant hype. But when they work, they can produce companies that are deeply embedded, hard to replace, and valuable for decades. That is the kind of doubling down that defines durable venture capital.
Conclusion
Nina Achadjian’s career at Index Ventures is a case study in conviction with context. She has backed and supported companies that modernize overlooked industries, automate complex workflows, and bring software into places where the old tools are finally running out of road. From ServiceTitan’s vertical SaaS success to newer bets in AI, robotics, and software for hardware, her work reflects a simple but powerful idea: the future is often hiding inside the least glamorous workflow in the building.
For founders, operators, and readers interested in venture capital, the lesson is clear. Look where others are not looking. Respect the customer’s pain. Build for depth before applause. And when the evidence gets stronger, do not just nod politely. Double down.